November 2026
The energy industry has been a driver of Alberta’s economy for decades, resulting in various infrastructure on the landscape (wells, facilities, and pipelines).
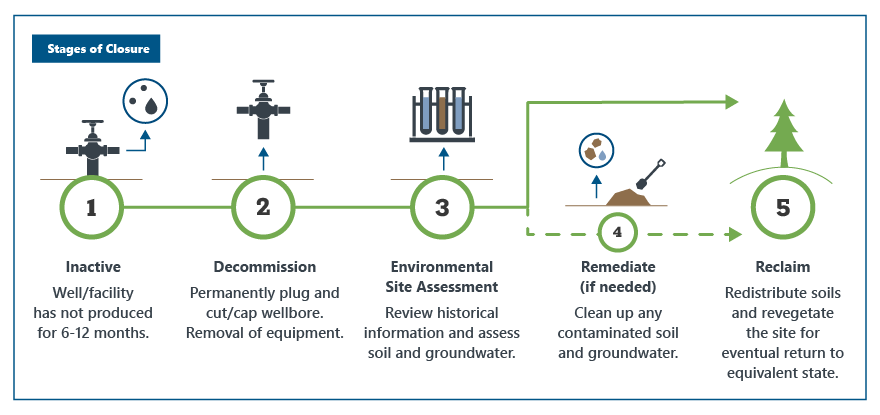
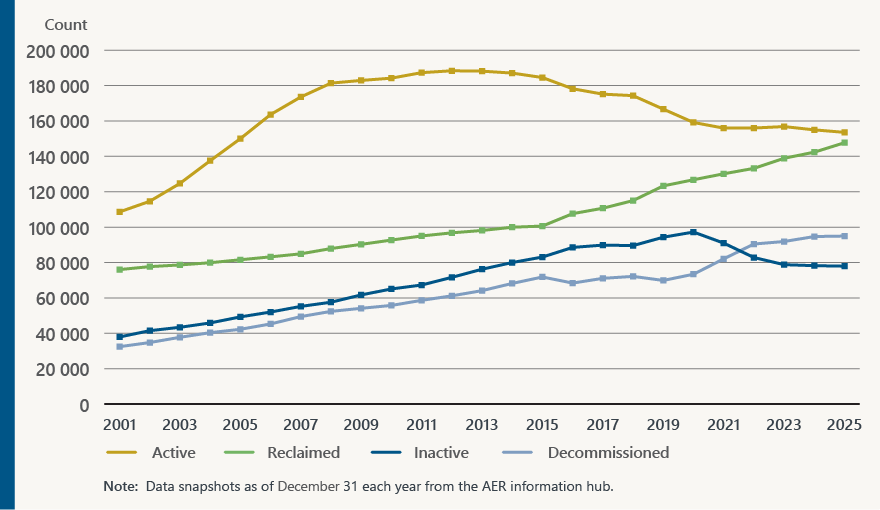
Ultimately, all infrastructure and energy development sites must be permanently and safely decommissioned, assessed, remediated if necessary, and reclaimed. These activities are known as “closure.” The obligation to carry out and pay for this work (known as “liability”) rests with industry. Figure 1 shows the various infrastructure stages of closure (active, inactive, decommissioned, and reclaimed).
Figure 1. Stages of Closure
Liability is associated with all energy infrastructure, regardless of its stage in the life cycle. However, close attention is paid to the amount of liability associated with inactive infrastructure as it no longer generates income for a licensee to pay closure costs.
Between 2001 and 2020, figure 2 shows that, while the closure rate remained steady, it did not keep pace with the higher drilling rate. Consequently, inactive infrastructure within the province increased 5% annually. If closure activities had been carried out at the same pace as energy development, the growth of inactive infrastructure may have been curtailed.
Since 2021, the inactive well trend has reversed and continues to trend downwards and may be levelling off. Although this is a positive trend, continued effort and focus by industry are essential to maintaining this downward trajectory.
Figure 2. Number of active, inactive, decommissioned, and reclaimed wells, 2001–2025
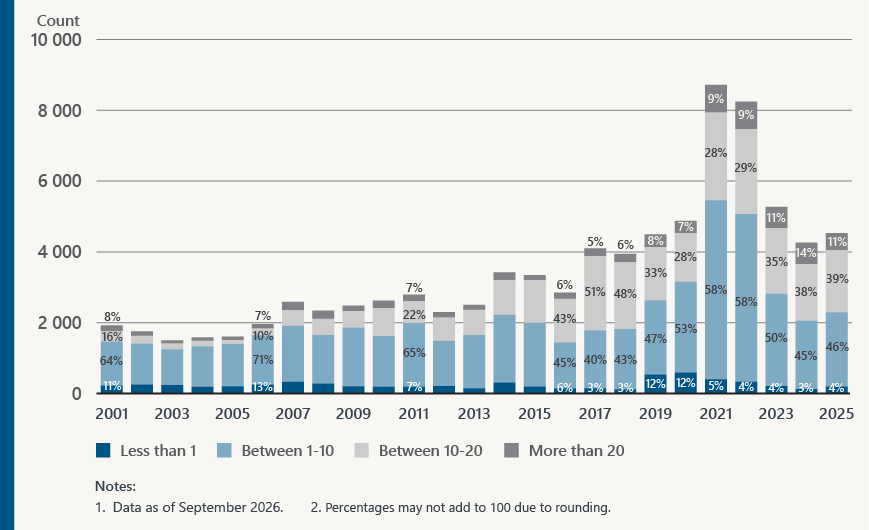
Focusing on the length of time a well has been inactive, figure 3 highlights that almost half of the current inactive wells have been inactive for more than 10 years. Figure 3 needs to be considered alongside figure 4, which shows a shift in closure prioritization toward the longer-term inactive wells after 2015. Comparing equal 10-year periods, the proportion of decommissioned wells that had been inactive for more than 10 years increased from approximately 25% during 2005–2014 to approximately 45% during 2015–2024. While the inactive-well inventory also aged over this period, the increase in the proportion of long-term inactive wells being decommissioned (approximately +19.7%) exceeded the increase within the inactive inventory itself (approximately +13.3%). This indicates progress in addressing older inactive inventory, while also showing that continued focus is needed to prevent long-term inactive wells from remaining on the landscape.
Figure 3. Inactive wells by years inactive 2001–2025
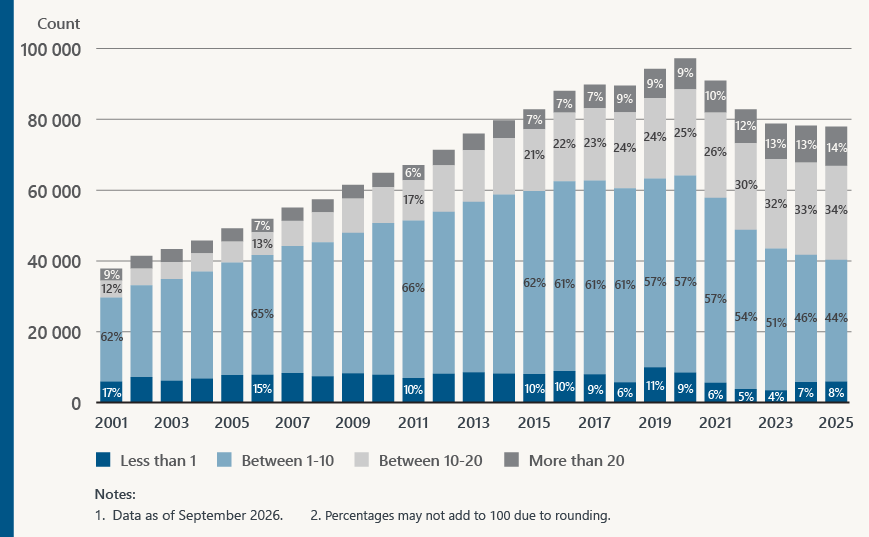
Figure 4. Industry decommissioned wells by years inactive, 2001–2025
We identify and track well and facility life-cycle status over time to help monitor industry’s progress on closure obligations and liability management. Our goal is for industry to convert inactive inventory in a timely manner to being decommissioned and reclamation certified.
Figure 5 shows the life-cycle status of wells from 2001 to 2025. Building on the trend that we saw in figures 3 and 4, we are seeing the shift over the last 10 years to reducing inactive wells, with increasing closure activity resulting in more abandoned and reclaimed wells.
Figure 5. Number of wells by life-cycle status, 2001–2025
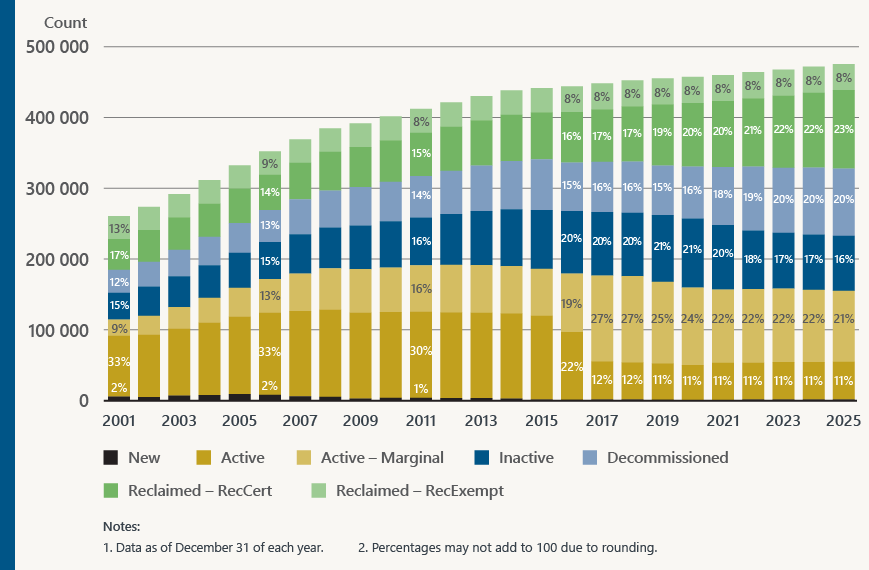
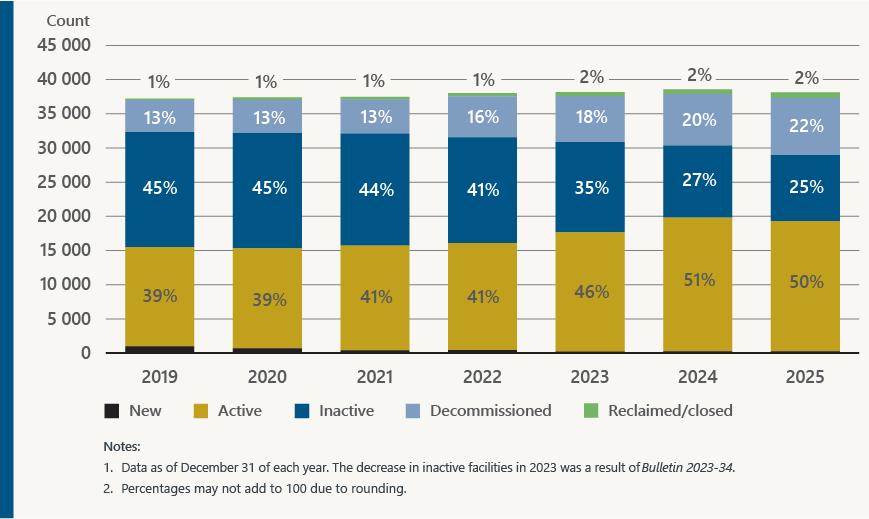
Figure 6 shows facilities from 2019 to 2025. We started identifying and tracking facility life-cycle status in 2019, with licensees validating and updating their life-cycle statuses in 2023 and 2024. Due to this effort, we have a better understanding of the operational life cycle of facilities in 2025, with half of them being active and over 20% of them being decommissioned, the first step to full closure.
Figure 6. Number of facilities by life-cycle status, 2019–2025
For more information on the pipelines we regulate, see our pipelines topic on our website.
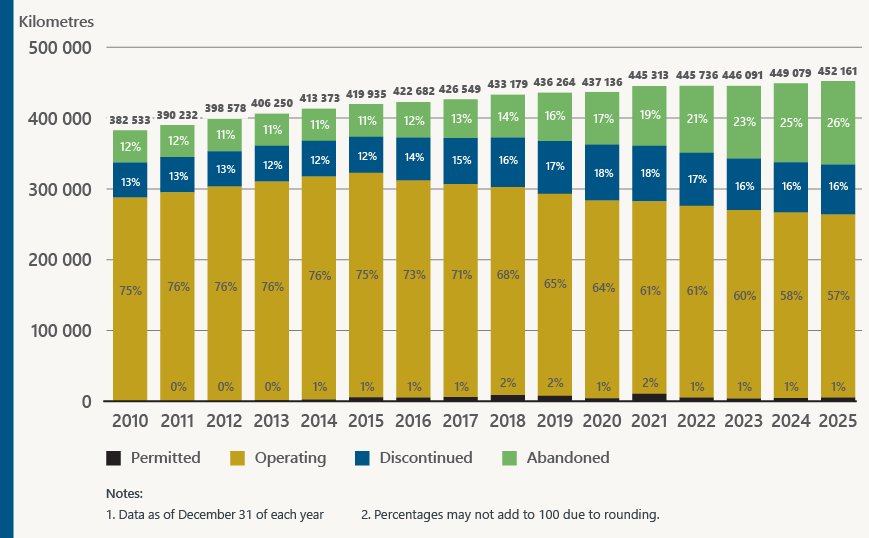
A pipeline licence is approved (“permitted” status) and then moves into operations (“operating” status). A pipeline status of “discontinued” corresponds to a suspended well. When the pipeline status is “abandoned,” it has met the criteria for abandonment. Licensees apply to change the pipeline licence status in accordance with the Pipeline Rules and Directive 065. The AER will then review the application and either approve or deny it based on relevant information. Figure 7 shows the total length of “operating” pipelines decreasing since 2016. In 2025, 57% of the pipeline length is “operating,” while 42% of the pipeline length is “discontinued” or “abandoned.”
The AER Is working to identify and track the life-cycle status of pipeline segments. This information will be integrated into future reports.
Figure 7. Combined pipeline length in kilometres by licence status
.